Why a UPS Part-Time Job Can Protect Your Retirement Savings
For early retirees navigating the gap years before Medicare, healthcare costs can quickly drain a portfolio. Taking a part-time position loading trucks at UPS can unlock valuable Teamsters union medical, dental, and vision benefits, offering a strategic alternative to expensive marketplace coverage.
The Financial Trap of ACA Marketplace Plans
Following the expiration of enhanced ACA premium tax credits, full-price marketplace coverage can become overwhelmingly expensive. For couples approaching Medicare eligibility at ages 63 and 64, insurers can charge up to three times what younger adults pay.
- The Subsidy Cliff: For 2027 coverage, the ACA subsidy threshold at 400% of the federal poverty level is $63,840 for an individual, meaning earning just one dollar more eliminates all premium assistance.
- The 401(k) Dilemma: Retirees with wealth tied up in pre-tax traditional accounts face a trap where every withdrawal or conversion counts as income, forcing them to choose between keeping subsidies and maximizing tax-efficient withdrawals.
Leveraging Union Coverage for 12% Roth Conversions
Securing coverage through the Teamsters union health plan cuts the direct link between taxable income and health costs. Once health premiums no longer depend on modified adjusted gross income (MAGI), retirees can intentionally convert pre-tax savings into a Roth account during low-tax years.
- Tax Bracket Optimization: A single filer can utilize the $16,100 standard deduction alongside the 12% tax bracket, which covers taxable income up to $50,400.
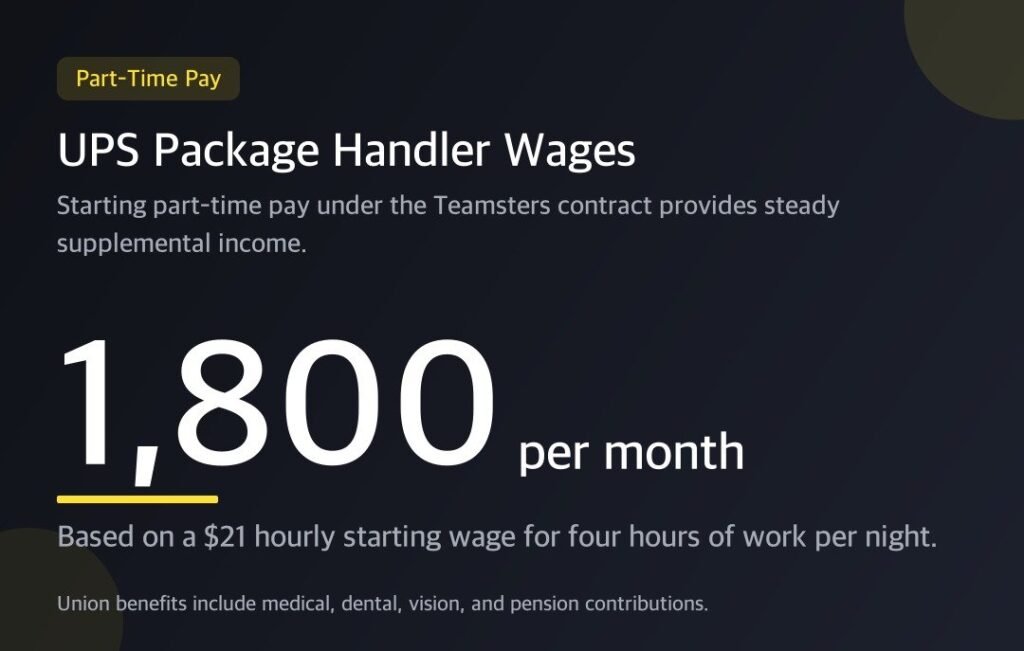
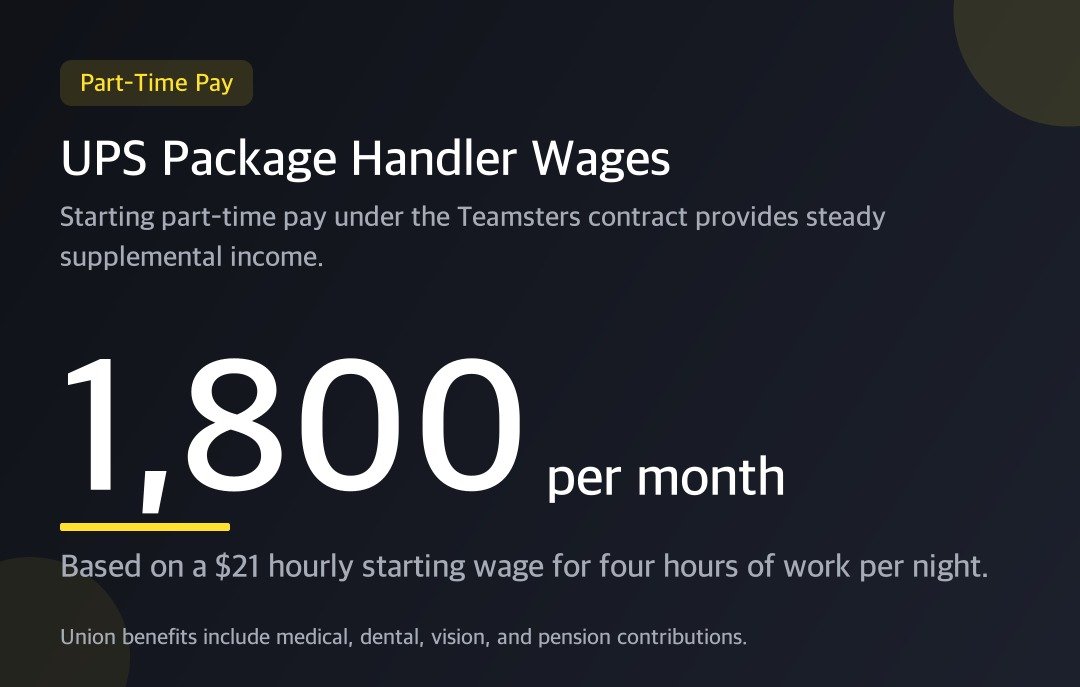
- Reducing Future RMDs: Factoring in a part-time UPS wage of about $21,600 annually ($1,800 a month at $21 an hour), retirees can open significant room to convert pre-tax savings at the 12% rate before required minimum distributions begin at age 75.
Key Considerations Before Starting
- Union Eligibility Rules: Local union plans set their own waiting periods and eligibility rules—often ranging from 90 days or longer—so maintaining marketplace or COBRA coverage in the interim is essential.
- Social Security Timing: Claiming Social Security early at age 63 permanently reduces lifetime benefits by about 25% compared to waiting until full retirement age at 67. With a part-time paycheck and a portfolio covering immediate expenses, delaying claims remains a critical priority.