What is the Social Security COLA for 2027?
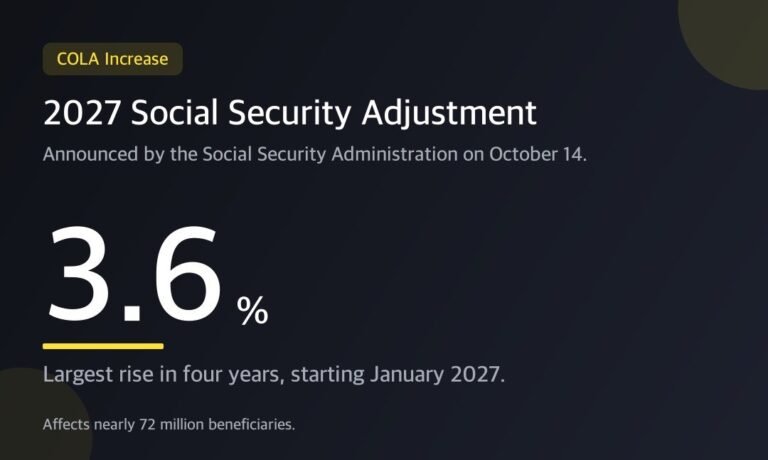
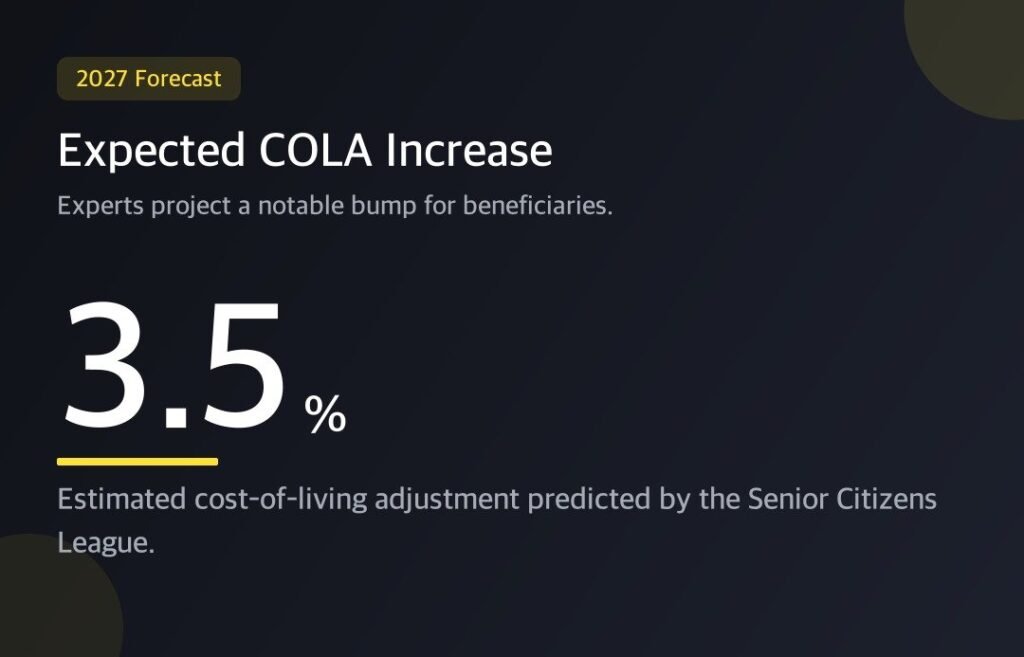
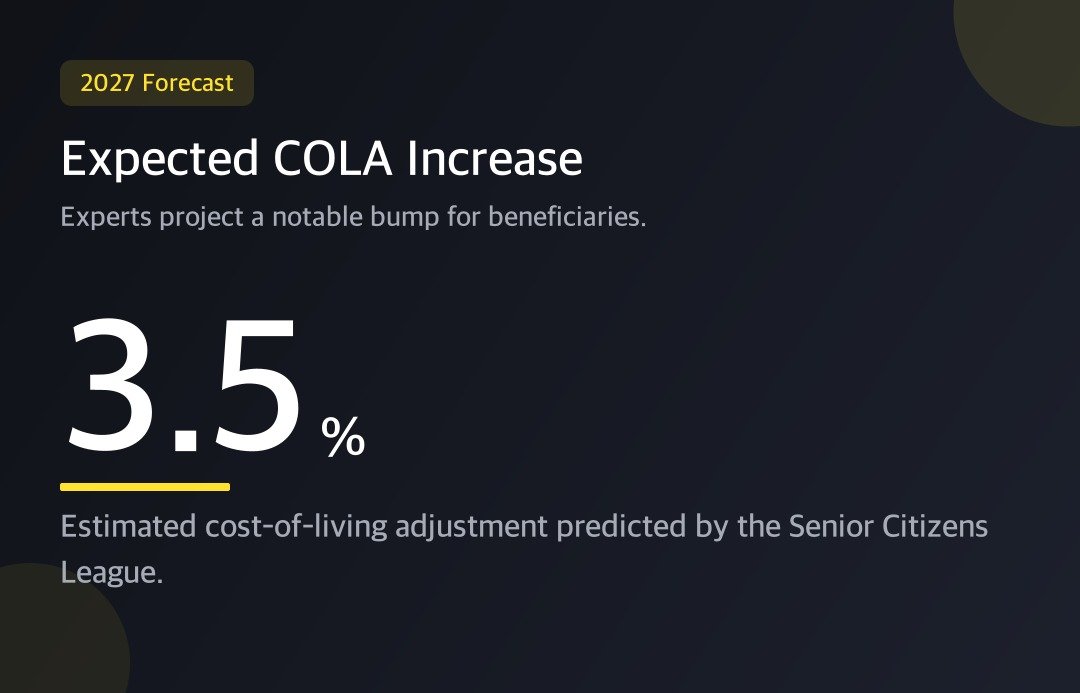
The Social Security Administration (SSA) is scheduled to announce its cost-of-living adjustment (COLA). According to forecasts by experts at the Senior Citizens League (TSCL), the SSA is on track to implement a 3.5% COLA. This adjustment would mark the largest annual benefits increase since fall 2022, when an 8.7% adjustment was announced.
When Does the 2027 COLA Take Effect?
The upcoming COLA will take effect starting in January 2027. It will primarily affect benefits issued to over 71 million Americans who claim retirement, disability, and survivor payments under the Social Security program. Additionally, the adjustment will apply to Supplemental Security Income (SSI) recipients, which is a separate SSA scheme for low-income individuals.
Impact on Retired Workers’ Monthly Benefits
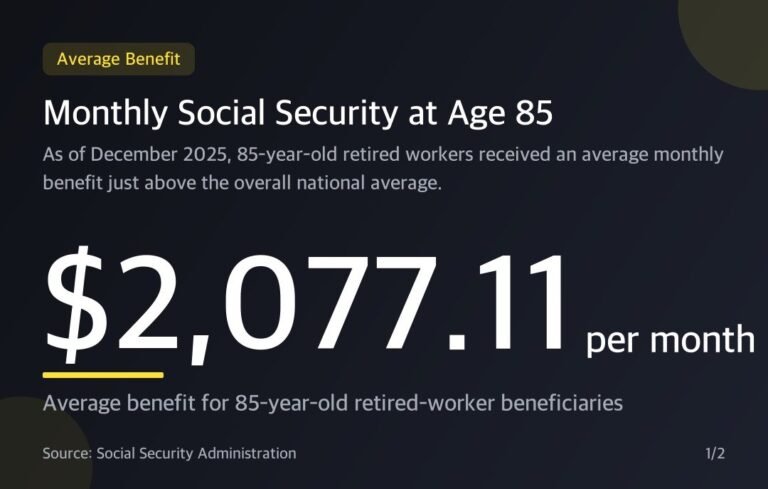
Retired workers make up 77% of Social Security recipients according to SSA statistics. Based on the SSA’s September fact sheet, the average monthly benefit stands at $2,087.52. If TSCL’s prediction holds true, a 3.5% adjustment would provide an approximate $73 increase to retired workers’ average monthly benefits.
How is the Social Security COLA Calculated?
The SSA determines the annual COLA by utilizing the Bureau of Labor Statistics’ (BLS) Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W).
- Data Comparison: The agency compares the CPI-W figures for July, August, and September of past and current years.
- Percentage Difference: If positive, the percentage difference is applied as the COLA for the following year.
- Previous Year Reference: For comparison, a comparison of figures at the start of 2026 resulted in a 2.8% increase, granting retired workers an average monthly bump of $56.
Criticism of the Calculation Method
Advocacy groups like TSCL have argued that the CPI-W focuses heavily on the purchasing experiences of working-age people rather than seniors. Because of this, it does not give enough weight to specific senior expenses such as healthcare and housing. TSCL contends that retirees would benefit more if the SSA used the BLS’s Consumer Price Index for Americans 62 Years of Age and Older (CPI-E), which typically reflects spending inflation rates two-tenths of a percentage point higher.